

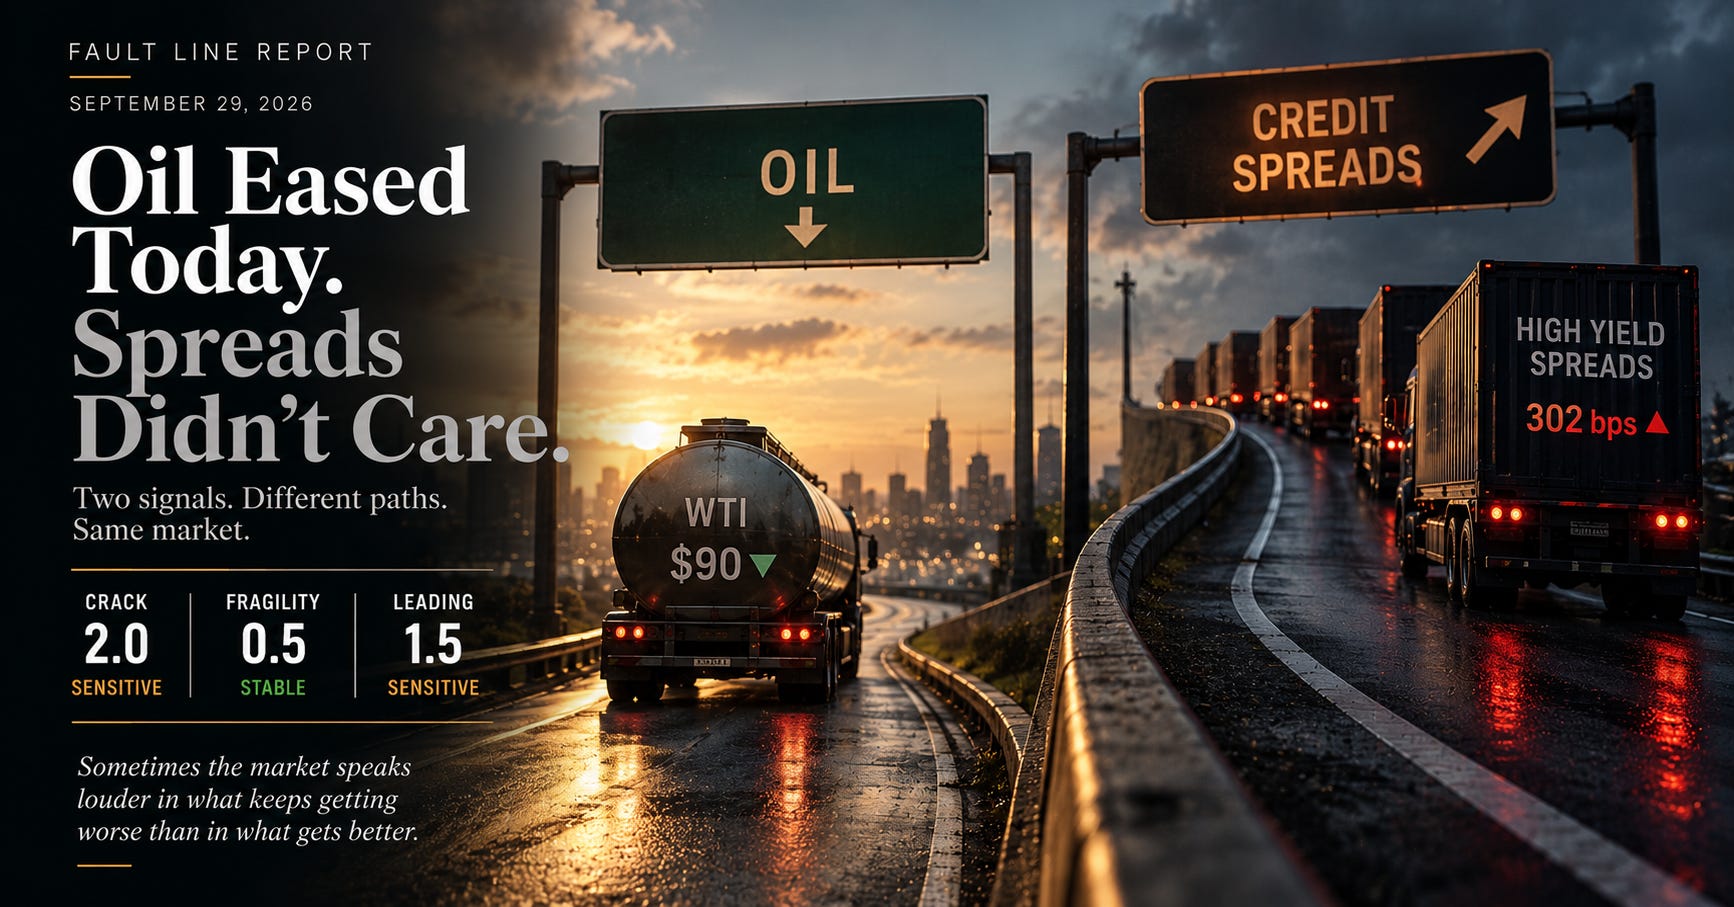
Something interesting happened this week that the headlines about oil and Iran didn’t capture. While WTI dipped back under $90 today — Brent’s still holding above $95, so my score didn’t move — high-yield credit spreads have been widening every single day since last Thursday. 268bps. 273. 280. 293. 302. Four straight days, and the pace is accelerating, not leveling off.
That’s the part worth sitting with. Oil calmed down today. Credit didn’t follow.
What’s actually driving it looks like the 30-year Treasury, not the Middle East. It’s climbed from 5.34% to 5.56% in under two weeks — a fast, sharp move, the kind that raises every company’s borrowing cost overnight and makes credit investors nervous about refinancing risk, independent of anything happening with oil. Rates and oil have been telling two different stories this week, and credit is listening to rates.
I want to be honest about scale here, because it’s easy to make four days of widening sound scarier than it is. 302bps is still historically tight. In 2008, the same spread reached over 2,100bps. In COVID, it hit 1,100bps in 23 trading days — the fastest move on record. We are nowhere near either of those, not close. What I’m watching isn’t the level, it’s the persistence: five consecutive days would be the first genuinely confirmed widening trend I’ve logged since I started tracking this daily back in July.
My shadow sensor hasn’t picked up on any of this yet — still the same four families active, 17 straight readings unchanged. The scorecard has, though: the last two matured observations came in negative, -1.02% and -1.19%, breaking a five-session positive streak. Small samples, but it’s the first time in this whole experiment that credit, the sensor, and the scorecard have all started drifting in the same direction at once, even if none of them have crossed a real threshold.
Nothing’s confirmed. Nothing’s triggered. But four days is one day short of five, and I’ll be watching tomorrow’s close closer than most days this month.
September 29, 2026